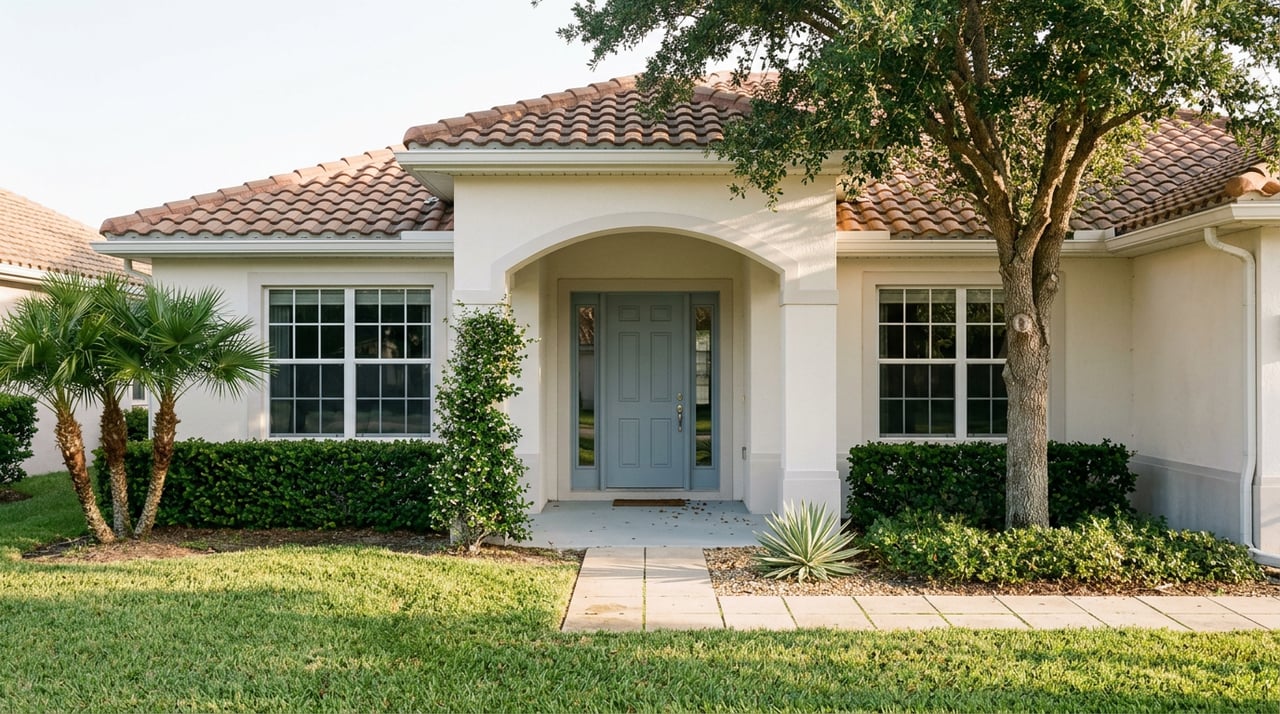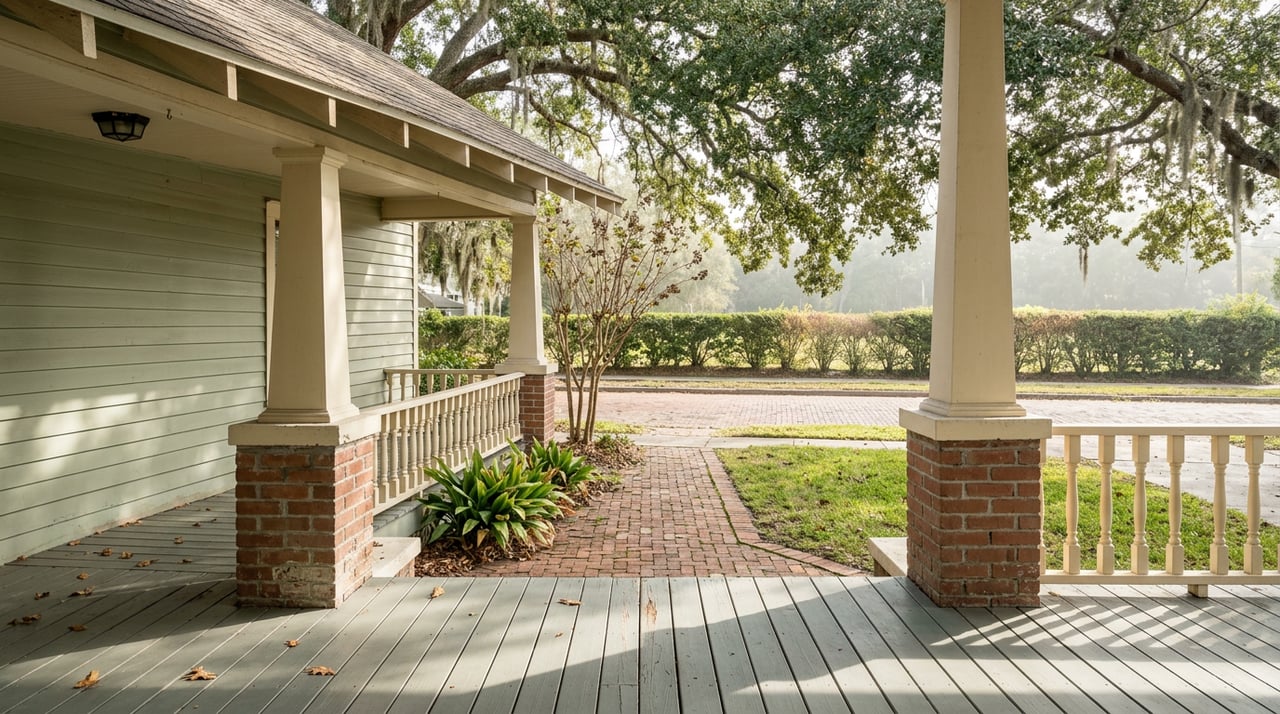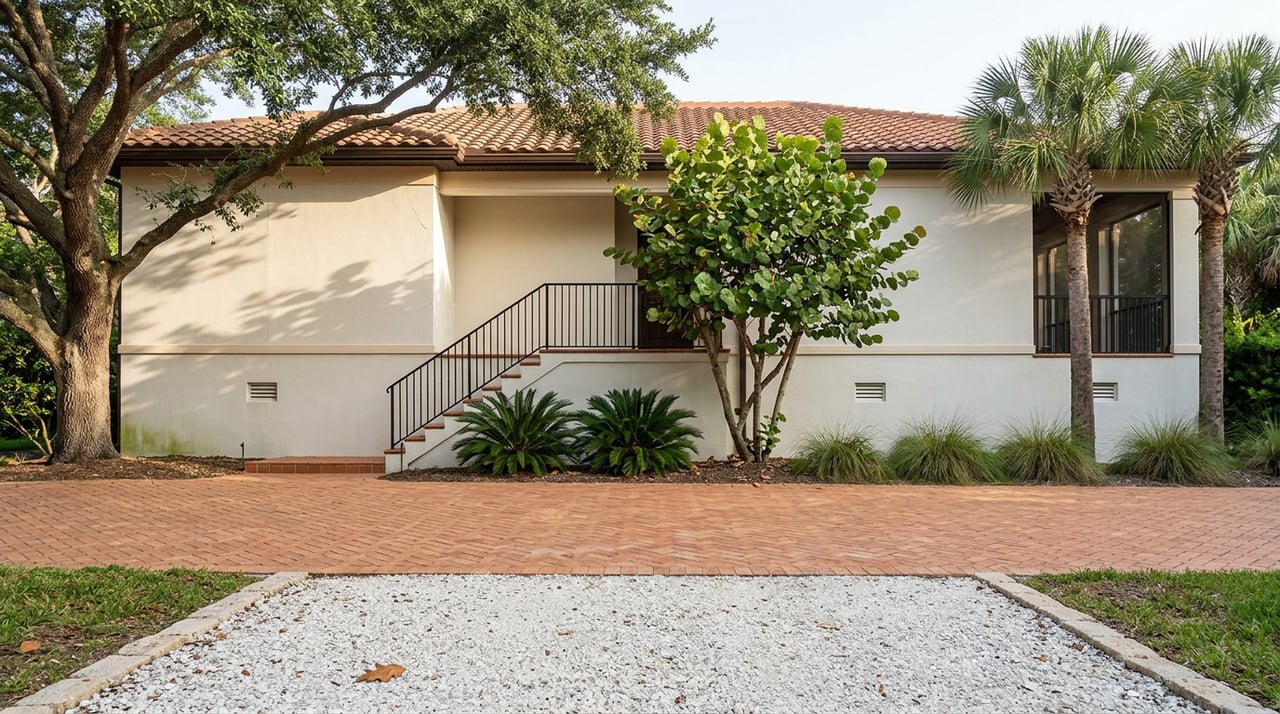
Two homes on the same stretch of Coffee Pot Boulevard NE can carry wildly different insurance bills. One owner pays a few hundred dollars a year for flood coverage nobody requires. Four doors down, another owner's lender mandates a policy that runs into five figures. Same zip code. Same brick streets. Same distance to the Vinoy. The listing photos look interchangeable. The FEMA flood map does not.
That gap is the real story behind why some St. Petersburg neighborhoods have held steady through 2026 while others have swung by double digit percentages in a single quarter. Buyers comparing Snell Isle to Crescent Lake, or Placido Bayou to Historic Uptown, tend to focus on the number that shows up first: the median sale price. That number is real, but it hides the mechanism that actually explains it. The mechanism is a FEMA flood zone boundary, and it can run through the middle of a neighborhood the same way a property line runs through a backyard.
What the letters on the flood map actually mean
Pinellas County properties mostly fall into three FEMA designations. Zone X is the low risk category, a 0.2 percent annual chance of flooding, and lenders do not require flood insurance here even though many owners still carry it. Zone AE carries a 1 percent annual chance, known as the 100 year floodplain, with a mapped Base Flood Elevation that determines how high a structure's lowest floor needs to sit. Zone VE adds wave action on top of that, the designation you find on direct Gulf and open bay frontage, and it carries the highest premiums in the county.
St. Petersburg's inland ridge, the higher ground running back from downtown toward 4th Street North, is mostly Zone X. The waterfront tier along the bay and its bayous is mostly AE. Some open water lots edge into VE. The zone isn't assigned by neighborhood name. It's assigned by elevation, and elevation doesn't respect a subdivision's marketing boundary.
Four neighborhoods, one line
Here is what that line looks like when you put four of St. Petersburg's named neighborhoods side by side.
| Neighborhood | Predominant flood zone | Flood insurance | 2026 price signal |
|---|---|---|---|
| Crescent Lake | Mostly Zone X | Optional for most homes | Steady, walkable inland market anchored by Crescent Lake Park |
| Historic Uptown | Mixed, parcel by parcel | Required on some streets, not others | Median value running near $578,000 as of mid-2026 |
| Snell Isle | Mostly AE, some VE on open bay lots | Typically $5,000 to $15,000+ a year | Median near $1.5 million in January 2026, a subsequent 2026 reading closer to $1.25 million average with 97 day average time on market |
| Placido Bayou | Nearly all parcels carry flood exposure | Required for most homes | Three month median fell 56.3 percent year over year through May 2026, on just 15 sales |
Crescent Lake sits on elevated terrain that keeps most of its housing stock out of the Special Flood Hazard Area entirely. The neighborhood's identity has nothing to do with that fact on the surface. People move there for the mile long walking loop around the lake, the tennis and pickleball courts, and Huggins Stengel Field, the ballpark inside the park where the Yankees and later the Mets held spring training and where Babe Ruth, Lou Gehrig, and Joe DiMaggio once played. The field earned a spot on the National Register of Historic Places in 2019. None of that has anything to do with insurance. But the elevation that keeps the park dry is the same elevation that keeps most of the surrounding blocks in Zone X, and that quiet fact is doing more to stabilize resale value than the ballpark ever will.
Historic Uptown tells a messier version of the same story. The neighborhood sits between 4th Street North, 16th Street North, 5th Avenue North, and 9th Avenue North, and its flood status genuinely varies by block. Streets near the lower lying edges of Round Lake carry mandatory flood insurance. Others, just a short walk away, do not. A buyer touring two bungalows on the same afternoon can get two entirely different insurance quotes, and neither the price nor the curb appeal will tell them why.
Snell Isle is the clearest example of the mechanism working in the opposite direction, toward volatility rather than stability. C. Perry Snell laid the island out in the 1920s as a Mediterranean planned community, and it remains anchored by the Vinoy Golf Club, an 18 hole course that stretches 6,626 yards at par 71. The Snell Isle Property Owners Association still runs the Crime Watch program and maintains the restored Snell Isle Park Plaza. None of that heritage changes the fact that most of the island sits in FEMA AE or VE zones, which means new construction has to elevate the finished floor above Base Flood Elevation, and existing owners pay for it every year in premiums that typically run $5,000 to $15,000 or more. That cost, layered onto a small luxury market where a handful of sales can swing the median, is why Snell Isle's numbers moved from a January 2026 median near $1.5 million to a subsequent 2026 reading closer to $1.25 million average with homes sitting on the market nearly 100 days. It isn't that the neighborhood lost its appeal. It's that a thin, insurance sensitive market moves harder in both directions than a stable inland one does.
Placido Bayou shows the same pattern from a different angle. The gated 360 acre community, with its ten retention ponds and roughly 637 homes, sits almost entirely inside high flood exposure territory. Its three month median sale price fell 56.3 percent year over year through May 2026, but that swing came from just 15 recorded sales, the kind of small sample where one or two high dollar closings can move the average by six figures in either direction. The volatility isn't a verdict on the neighborhood. It's a symptom of a small, insurance heavy luxury market where price discovery happens slowly and unevenly.
When Hurricanes Helene and Milton drew the line for free
Old Northeast, just south of Snell Isle, makes the flood zone split visible without a map at all. The neighborhood's central grid, running back toward 4th Street North, sits largely in Zone X. Its waterfront tier, Coffee Pot Boulevard, Bayshore Drive, North Shore Drive, and the easternmost blocks along the bay, sits in Zone AE, where flood insurance is mandatory with any federally backed mortgage. When Hurricanes Helene and Milton hit within two weeks of each other in the fall of 2024, that boundary stopped being theoretical. The waterfront blocks took storm surge. Most of the interior high ground did not. Two homes four blocks apart can differ by thousands of dollars a year in insurance, and in a real storm season, that same line decided which ones took on water.
The renovation trap almost nobody sees coming
Here's the friction that catches buyers who think they've done their homework. St. Petersburg enforces a substantial improvement threshold at 49 percent of a home's market value, one point stricter than the federal 50 percent floor. If a renovation or repair project in a flood zone reaches that share of the property's value, the entire structure has to be brought up to current flood code, which usually means elevating it. On a 1920s bungalow in a historic district, that requirement collides directly with preservation rules that often prohibit exactly the kind of structural changes elevation requires. A buyer planning a major renovation on a contributing historic home in a flood zone can end up caught between two agencies with conflicting demands, and it is the single most expensive surprise in these neighborhoods precisely because it is entirely avoidable if you know the number and the zone before you make an offer.
What to ask before you tour anything
Before touring a home in any of these neighborhoods, pull the parcel's flood zone directly from FEMA's Flood Map Service Center rather than relying on the neighborhood's general reputation. Ask for the elevation certificate if one exists, and if it doesn't, decide upfront whether you'll order one during your inspection period. Get an actual flood and wind insurance quote before you write an offer, not an online estimate. Ask directly whether the specific address has flooded, since Florida disclosure law requires sellers to reveal known flooding history. And if any renovation is part of your plan, ask whether the project's cost would trigger the city's 49 percent substantial improvement threshold before you fall in love with the floor plan.
A few direct questions
Does Zone X mean a home will never flood? No. Zone X reflects a lower mapped annual chance of flooding, not zero risk. Homes in Zone X areas of Pinellas County have taken on water during recent storms, and many owners still carry optional flood coverage even where it isn't required.
How do I find the flood zone for one specific address, not just the neighborhood? FEMA's Flood Map Service Center lets you search by exact address. That matters because, as Old Northeast and Historic Uptown both show, the zone can change from one block to the next inside a single named neighborhood.
Does a lower flood risk automatically make a better investment? Not automatically. Lot size, school zoning, walkability, and personal fit all matter too. But across these four neighborhoods, flood zone is the variable that most directly explains why some St. Petersburg addresses have held steady prices through 2026 while others have moved by double digits within a single quarter.
If you're weighing one of these neighborhoods against another, the flood zone conversation is worth having early, before a house shows up on your shortlist for the wrong reasons. Judy Anderson has spent years working these specific streets and can walk you through what a parcel's actual flood status means for your budget and your offer. Let's Connect.